NEWS
Ayushman Card Rules 2026: Can You Get Free Treatment After Using the Full ₹5 Lakh PM-JAY Limit?
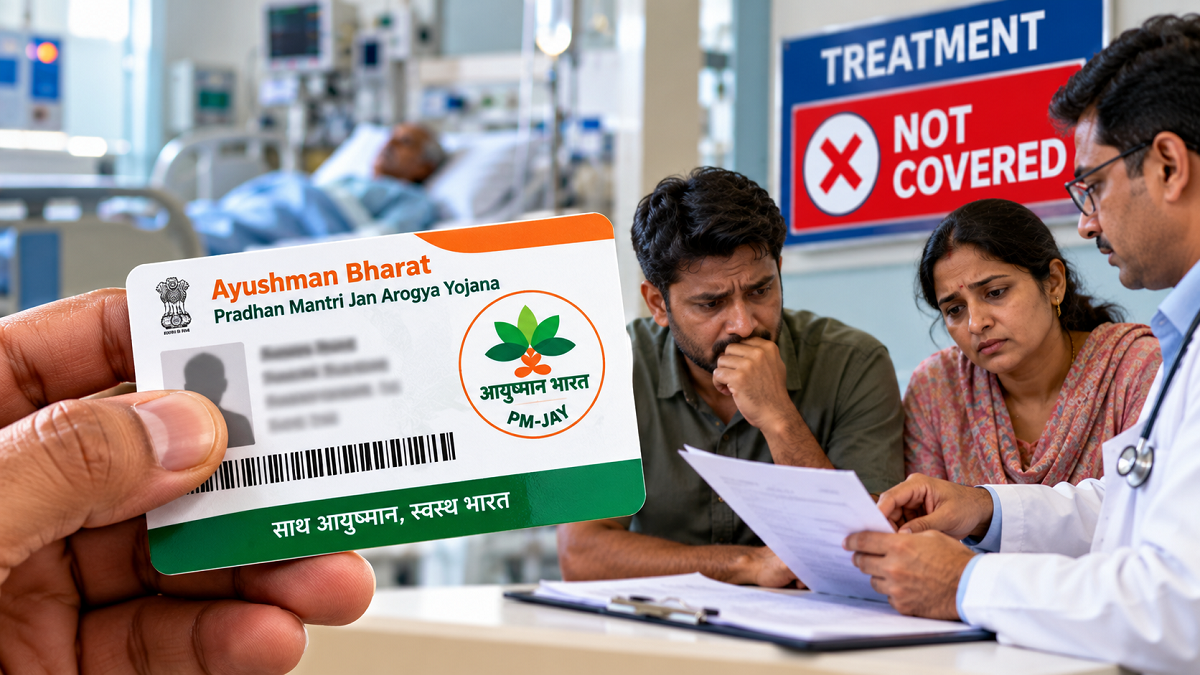
Ayushman Bharat PM-JAY Update 2026: Medical treatment can place a significant financial burden on Indian families, particularly when a serious illness requires surgery, hospitalisation or prolonged care. To help eligible households manage these expenses, the Government of India introduced the Ayushman Bharat Pradhan Mantri Jan Arogya Yojana (AB PM-JAY), which provides cashless hospital treatment coverage of up to ₹5 lakh per family per year.
However, an important question arises when a family uses its entire annual coverage before the benefit period ends. Will the Ayushman Card stop working? Can another family member still receive free treatment? And when will the ₹5 lakh coverage become available again?
Understanding these rules is essential for beneficiaries who depend on the scheme for expensive medical procedures. Here is what families should know about the annual coverage limit, renewal process and treatment options when their available benefits have been exhausted.
Ayushman Bharat PM-JAY: How Does the ₹5 Lakh Health Cover Work?
Ayushman Bharat PM-JAY is a government-funded health assurance scheme designed to provide financial protection against eligible secondary and tertiary hospitalisation expenses.
Under the standard scheme, an eligible family can receive up to ₹5 lakh in cashless hospitalisation benefits during the applicable annual coverage period.
The scheme covers specified treatment packages at hospitals empanelled under PM-JAY, subject to its eligibility conditions and operational rules.
One important feature is that the standard ₹5 lakh benefit is generally provided on a family-floater basis.
This means the coverage is shared among eligible family members rather than being allocated separately to every individual.
For example, if one family member receives treatment costing ₹3 lakh under the scheme, the family would generally have ₹2 lakh remaining for other covered treatment during that benefit period.
Similarly, if multiple family members require hospitalisation, their eligible expenses are ordinarily adjusted against the same available family coverage.
Special beneficiary categories or additional state-funded benefits may follow different arrangements.
What Happens When the Entire ₹5 Lakh Ayushman Card Limit Is Exhausted?
Suppose a family member undergoes major surgery or requires prolonged hospitalisation, resulting in the full ₹5 lakh annual coverage being utilised.
In such circumstances, the family may no longer have sufficient standard PM-JAY coverage available for additional treatment during the same benefit period.
This does not automatically mean that the Ayushman Card becomes permanently invalid.
The card may remain associated with the beneficiary's eligibility, but the amount available for further cashless treatment under the standard annual limit could be exhausted.
Consequently, another family member requiring hospitalisation might not be able to claim additional expenses against the already-used coverage.
However, the actual situation depends on the applicable scheme rules, the beneficiary category and whether any additional benefits are available.
Families should therefore confirm their remaining balance before arranging further treatment.
Does the Ayushman Card Stop Working After ₹5 Lakh Is Used?
Many beneficiaries believe that once the annual coverage limit is exhausted, their Ayushman Card becomes permanently blocked or cancelled.
That is not necessarily correct.
Exhausting the available coverage and losing eligibility under the scheme are two different situations.
An eligible beneficiary may continue to hold a valid Ayushman Card even when the standard family coverage has been fully utilised for the current benefit period.
However, holding a valid card does not guarantee that unlimited additional cashless treatment will be available.
Further treatment claims depend on the remaining benefit amount, applicable annual coverage rules and any additional entitlements.
Beneficiaries should not assume that another ₹5 lakh will automatically become available immediately after the previous limit has been exhausted.
When Does the Ayushman Bharat ₹5 Lakh Coverage Renew?
The PM-JAY benefit is structured around an annual coverage entitlement.
However, beneficiaries should verify the renewal arrangements applicable to their coverage instead of assuming that every family's limit necessarily resets on April 1.
The applicable annual period and benefit accounting arrangements should be confirmed through official PM-JAY support channels or the hospital's Ayushman help desk.
This is especially important for families whose coverage has been substantially utilised.
Before scheduling expensive treatment, beneficiaries should confirm whether the next annual entitlement is available and whether any pending treatment claims have already been deducted from their balance.
The hospital's designated scheme representative can assist with checking the relevant information.
Can Another Family Member Receive Free Treatment After the Limit Is Exhausted?
Under the standard family-floater arrangement, the ₹5 lakh annual benefit is shared among eligible family members.
For example, consider a family of four covered under PM-JAY.
If one member undergoes surgery costing ₹4 lakh, approximately ₹1 lakh would ordinarily remain available for other covered treatment during that benefit period.
If another family member subsequently requires hospitalisation costing ₹2 lakh, the remaining standard coverage may not be sufficient to cover the entire expense.
If the complete ₹5 lakh has already been utilised, further claims against that exhausted standard entitlement would generally not be available until coverage becomes available under the applicable rules.
However, families should check whether additional state-specific coverage, special eligibility provisions or other assistance arrangements apply.
Can Patients Still Receive Free Treatment After Their PM-JAY Balance Reaches Zero?
Once the standard coverage is exhausted, additional hospital expenses may not be payable under that same benefit limit.
Nevertheless, patients should not automatically conclude that no medical assistance is available.
Depending on their circumstances, they may be eligible for other government health programmes, state-funded assistance or hospital-supported financial aid.
Some states operate additional health protection arrangements that may provide benefits beyond the standard central PM-JAY entitlement.
Availability and eligibility differ by programme and location.
Beneficiaries should contact the hospital's Ayushman help desk to understand the options available in their specific case.
Patients requiring urgent medical attention should seek appropriate medical care without delaying treatment solely to resolve an insurance balance question.
How to Check the Remaining Ayushman Card Coverage
Beneficiaries can seek assistance from an empanelled hospital's Ayushman help desk to understand their available benefits.
The hospital may help verify the patient's eligibility, applicable treatment package and available coverage.
Before undergoing a planned procedure, families should confirm whether the proposed treatment is included in the scheme's approved package list.
They should also ask whether any additional expenses could arise if the available coverage is insufficient.
The official PM-JAY helpline, 14555, can be used to seek guidance about scheme-related questions.
Important Things to Verify Before Hospitalisation
| What to Check | Why It Matters |
|---|---|
| Ayushman Card eligibility | Confirms whether the patient qualifies for scheme benefits |
| Remaining family coverage | Helps determine the available amount for treatment |
| Hospital empanelment | Confirms whether the hospital participates in the scheme |
| Treatment package | Establishes whether the required procedure is covered |
| Annual benefit period | Helps clarify when coverage may become available again |
| Additional scheme benefits | Identifies possible state-specific or special entitlements |
Verifying these details in advance can reduce confusion and unexpected expenses during hospitalisation.
What Should You Do If a Hospital Refuses Cashless Treatment?
If an empanelled hospital refuses cashless treatment, beneficiaries should first ask for a clear explanation.
There may be several reasons, including exhausted coverage, treatment package restrictions, eligibility issues or administrative difficulties.
Patients can approach the hospital's Ayushman help desk for clarification.
If the issue remains unresolved, they can seek assistance through official PM-JAY grievance and support channels.
Beneficiaries should retain relevant medical documents, treatment estimates and communication records when raising a complaint.
Ayushman Card Rules 2026: What Every Beneficiary Should Remember
Ayushman Bharat PM-JAY provides valuable financial protection to eligible families by offering up to ₹5 lakh in standard annual cashless hospitalisation coverage.
However, the benefit is generally shared across eligible family members, and it is not an unlimited treatment facility.
Once the available annual coverage has been fully utilised, further claims against that same entitlement may not be possible until benefits become available under the applicable rules.
Importantly, using the entire ₹5 lakh limit does not automatically mean that the Ayushman Card itself becomes permanently invalid.
Families should verify their remaining coverage, renewal arrangements and any additional assistance available before planning further hospital treatment.
Disclaimer: This article explains the standard PM-JAY coverage framework based on the supplied information. Additional benefits, renewal arrangements and treatment eligibility may vary according to beneficiary category and applicable state schemes. Patients should confirm their individual entitlements with official PM-JAY authorities or an empanelled hospital.