NEWS
Understand which UPI transactions may attract a notice; understand the rules for cash transfers.
If a UPI transaction or a large cash deposit at a bank doesn't automatically result in a tax notice, the Income Tax Department may investigate the source of the funds. Therefore, it's important to maintain accurate bank records, receipts, and income records.
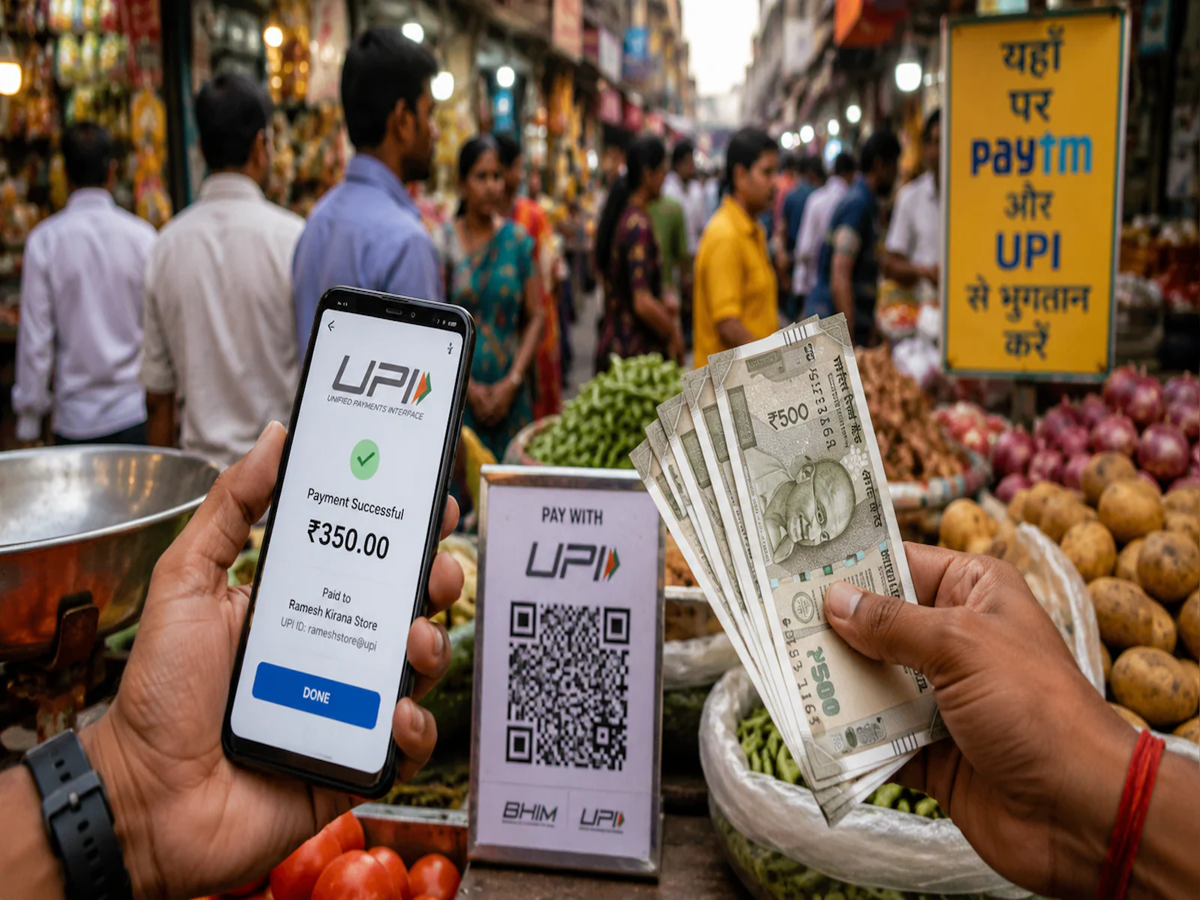
Understand which UPI transactions may attract a notice; understand the rules for cash transfers.
Large deposits into your bank account or frequent inflows via UPI aren't in themselves grounds for a tax notice. However, if there's a significant discrepancy between the amount deposited into your account and your declared income, the Income Tax Department may request information about the source of the funds. Therefore, it's important not only to make digital payments but also to maintain accurate records of transactions.
Under the Income Tax Department's Statement of Financial Transactions (SFT) rules, cash deposits totalling Rs 10 lakh or more in specified non-current and non-term-deposit accounts, including savings accounts, in a financial year are reported.
Meanwhile, cash deposits of ₹50 lakh or more in a current account are subject to reporting. It's important to note that reporting does not necessarily result in a notice; the department can investigate the transaction if necessary. These cash deposit limits are not directly applicable for UPI, NEFT, RTGS, and IMPS.
Is there any limit on UPI transactions?
People generally believe that the Income Tax Department can issue a notice if you transact large amounts through UPI in a year. However, there's no set rule for issuing a notice based solely on the total amount of UPI transactions. In fact, the department can check whether the funds deposited into your account match your declared income.
For example, if a person reports an annual income of ₹1.2 million (1.2 million rupees) but has ₹4 million (4 million rupees) deposited in their bank account throughout the year, the source of the additional amount may be questioned. This could include money from family or transactions between friends, which are not always taxable income.
Taking money from others and sending it forward can also become a question.
Sometimes people transfer money to their own accounts to friends, relatives, or for group purchases. This isn't wrong in itself, but repeatedly receiving large sums and then immediately sending them forward can raise questions about the nature of the transaction.
If the source of the money in your account is unclear, simply forwarding the money doesn't absolve you of responsibility. Therefore, it's important to keep proof of who sent the money, for what purpose, and to whom it was transferred.
What to do to avoid notice?
Keep bank statements, payment receipts, invoices, and other documents related to the source of funds. Accurately disclose your actual income in your ITR and distinguish personal from business income. Remember, large transactions are not automatically tax evasion; having accurate information and documentation makes it easier to provide clarifications if necessary.
Why should freelancers and small businesses be cautious?
Freelancers, tutors, and small businesses often receive payments via UPI. While payments received in exchange for services or business can generally be considered income, money received to split a bill between friends doesn't automatically constitute income.
Problems can arise when personal and business payments are deposited into the same account and their accounting is unclear. Therefore, it's helpful to keep separate records of business income, issue bills as needed, and preserve bank statements.