Getting a loan has become much faster than it was a few years ago. Banks, non-banking financial companies (NBFCs) and digital lending platforms can now process certain loan applications quickly, making credit easily accessible for eligible borrowers.
However, faster approval should not mean accepting a loan without understanding its terms. Borrowers sometimes focus only on the loan amount and advertised interest rate while overlooking processing charges, penalties and other conditions. These costs can significantly affect how much a borrower ultimately pays.
This is where the Key Facts Statement (KFS) becomes important. The Reserve Bank of India (RBI) has prescribed a KFS framework to improve transparency and help borrowers understand important loan terms before entering into a credit agreement.
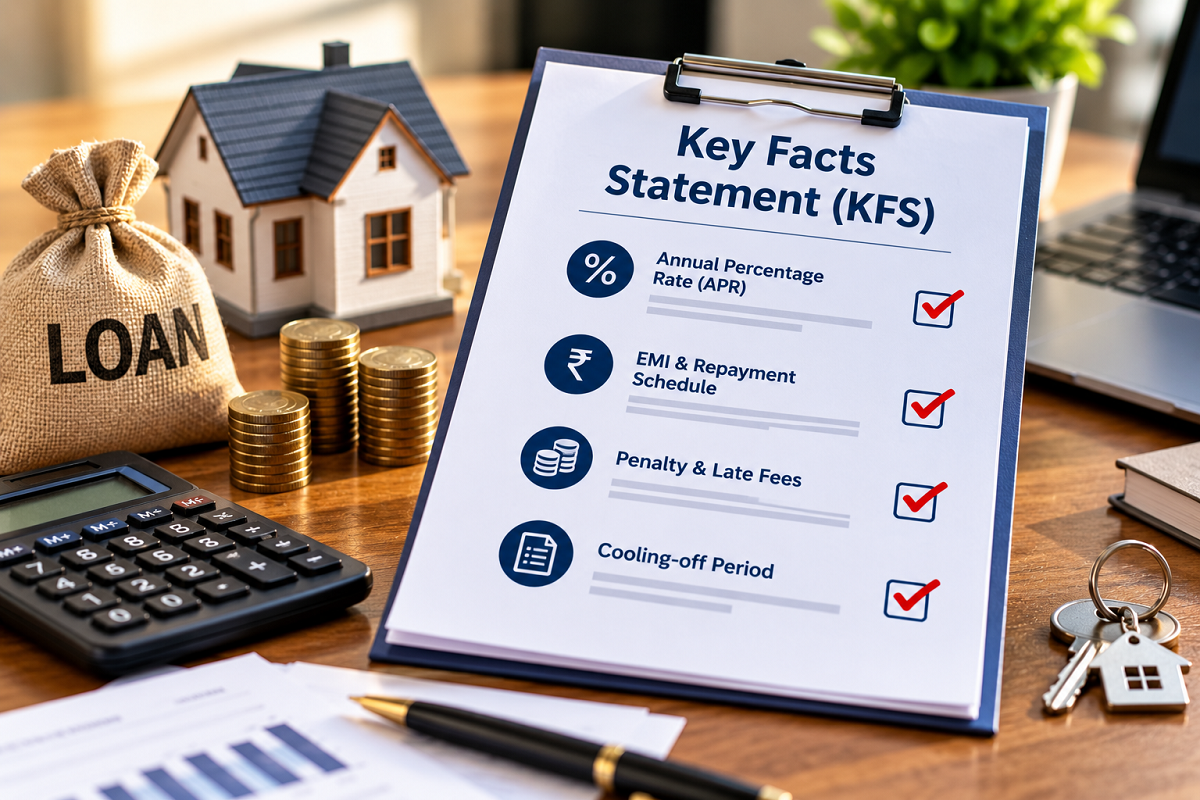
If you are considering a loan, here are four important areas you should examine carefully in the KFS.
What Is a Key Facts Statement?
A Key Facts Statement is a standardised summary containing important information about a loan. It is intended to present essential borrowing terms in a format that customers can understand more easily before accepting the loan.
Depending on the type of loan and applicable regulatory requirements, the KFS contains key details such as the sanctioned loan amount, interest-related information, Annual Percentage Rate (APR), repayment schedule and applicable charges.
Instead of relying only on advertisements or verbal explanations from a lender, borrowers can use the KFS to understand and compare the financial implications of a loan.
1. Don't Look Only at the Interest Rate — Check the APR
One of the first figures borrowers should examine is the Annual Percentage Rate (APR).
The advertised interest rate alone may not provide a complete picture of borrowing costs. APR is intended to provide a broader measure of the annual cost of the loan by taking into account the interest rate and applicable charges included under the regulatory methodology.
For example, two lenders may advertise similar interest rates, but differences in other charges could mean the overall borrowing costs are not identical.
Therefore, when comparing loan offers, borrowers should pay attention to the APR instead of making a decision based solely on the headline interest rate.
2. Examine the EMI and Complete Repayment Schedule
A loan may appear affordable when you look only at the monthly EMI. However, the EMI should always be considered together with the loan tenure and total repayment obligation.
The KFS should help borrowers understand the repayment structure, including the instalment amount and repayment schedule.
Before accepting a loan, calculate whether the EMI comfortably fits within your monthly budget. You should also consider how much you are expected to repay over the entire tenure rather than focusing only on the amount borrowed.
A smaller EMI is not automatically a cheaper loan. Extending the repayment period can reduce the monthly burden but may increase the total interest paid over time.
3. Check Penalties, Late Payment Rules and Other Charges
Missing an EMI can make a loan more expensive.
Borrowers should therefore check how delayed payments are treated and what penal charges may apply in case of default or non-compliance with the loan terms.
It is equally important to check the conditions related to early repayment.
If you expect to repay the loan before the original tenure ends, find out whether any prepayment or foreclosure conditions or charges apply to your particular loan.
The applicable rules can differ depending on the lender, loan category and regulatory requirements. Never assume that all loans carry the same prepayment conditions.
4. Understand the Cooling-Off Period for Digital Loans
People taking loans through digital lending channels should also pay attention to the cooling-off or look-up period applicable under the relevant digital lending framework.
This facility is intended to give borrowers a specified period during which they can exit an eligible digital loan by paying the principal and proportionate APR, subject to the applicable rules and permitted charges.
The exact conditions should be checked in the loan documents and KFS.
This provision can be particularly important when a borrower accepts a digital loan quickly but subsequently decides that the loan is unsuitable.
Why Reading the KFS Can Save You From Surprises
A KFS can make it easier to understand what you are actually agreeing to before taking a loan.
It can help you evaluate the overall cost, understand the repayment structure and identify charges that might otherwise be overlooked.
The document can also make it easier to compare competing offers from banks and NBFCs. Instead of comparing only the interest rates advertised by lenders, borrowers can examine the APR, repayment terms and applicable charges together.
That comparison can help prevent a seemingly attractive loan offer from turning into an unnecessarily expensive financial commitment.
Don't Make This Mistake Before Accepting a Loan
Instant approval can be convenient, particularly when money is urgently required. But speed should never replace due diligence.
Do not accept a loan simply because an app or lender says the money can be transferred quickly.
Before signing or digitally accepting the loan agreement, carefully review the KFS and check the APR, EMI, repayment schedule, penalties, applicable charges and other important conditions.
Also ensure that the information in the final loan agreement is consistent with what was disclosed to you.
If you do not understand a particular charge or condition, ask the bank, NBFC or regulated lender for clarification before accepting the loan.
A few extra minutes spent understanding the KFS can help you choose a loan based on its actual cost and conditions rather than being influenced only by a low advertised interest rate or instant approval promise.