Business
IRDAI Health Insurance Update 2026: Policyholders May Soon Track Claims Live and Get Faster Settlements
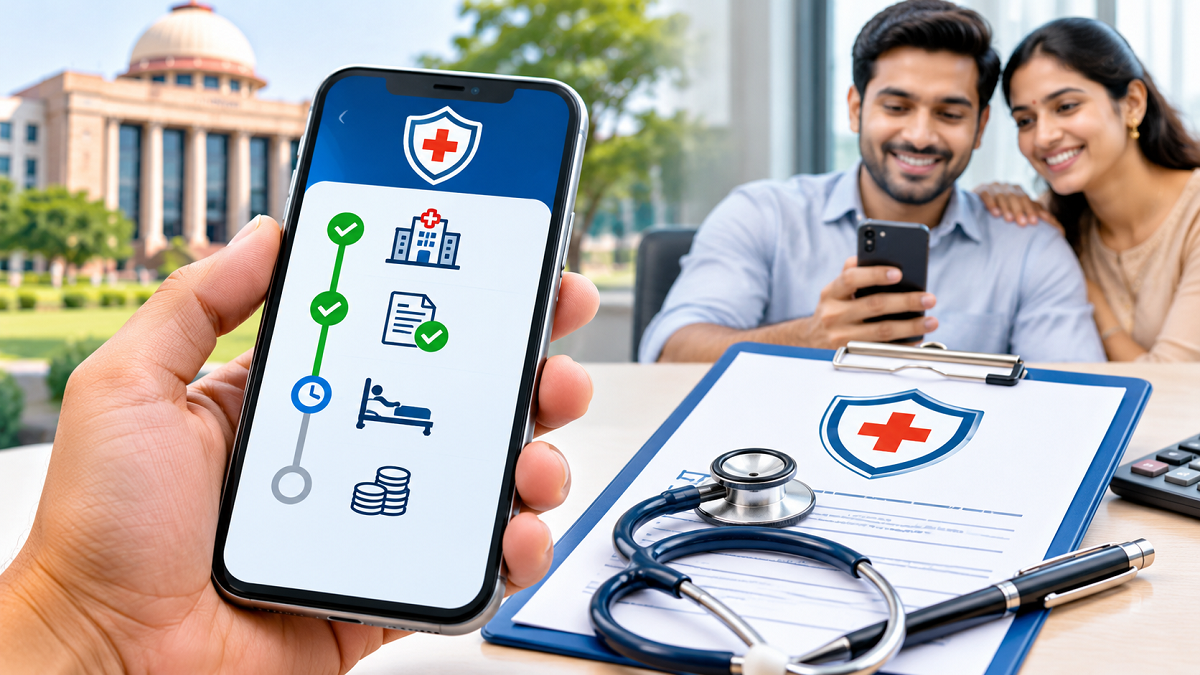
Health Insurance Rules 2026: Health insurance policyholders in India could soon benefit from a more transparent and convenient claim settlement process. The Insurance Regulatory and Development Authority of India (IRDAI) is reportedly working on several reforms designed to improve customer experience, reduce unnecessary paperwork and make insurance companies more accountable.
One of the most significant proposed changes is a real-time health insurance claim tracking system. If implemented, the facility would allow policyholders to monitor their claims through their smartphones without repeatedly contacting insurance companies or visiting their offices.
The proposed improvements also focus on claim settlement transparency, standardised rejection procedures, faster documentation and the possible integration of Ayushman Bharat Health Account (ABHA) identification.
Here is everything policyholders should know about the reported IRDAI health insurance reforms.
1. Real-Time Health Insurance Claim Tracking Through Mobile Phones
One of the major initiatives under consideration is the introduction of a digital system that allows customers to follow the progress of their health insurance claims.
According to the report, a dedicated working group will examine how such a system can be developed and implemented.
The proposed facility could provide policyholders with important information, including:
- The current status of their cashless hospitalisation request.
- The amount approved by the insurance company.
- Updates related to hospital discharge and final authorisation.
- The time taken to process and settle the claim.
- Notifications about claim approvals and other important developments.
Currently, patients and their families may need to contact hospitals, insurance companies or third-party administrators to understand why a claim is pending.
A centralised tracking facility could make this process easier by providing timely information through a digital interface.
This would be particularly useful during hospitalisation, when patients and their families are already dealing with medical and financial concerns.
However, the proposed real-time tracking facility should not be treated as universally available until its implementation is officially announced.
2. Actual Claim Payments May Receive Greater Importance
IRDAI is also reportedly considering changes to how insurers' claim settlement performance is evaluated.
A commonly used measure is the claim settlement ratio, which helps customers understand how many claims an insurer has settled during a particular period.
However, the number of claims settled does not necessarily reveal how much money policyholders actually received.
For example, consider a customer who submits a health insurance claim of ₹5 lakh.
If the insurer approves only ₹3 lakh, the claim may still be recorded as settled under certain reporting methods, even though the customer receives less than the requested amount.
Here is an illustration:
| Claim Details | Amount |
|---|---|
| Total Claim Submitted | ₹5,00,000 |
| Amount Approved by Insurer | ₹3,00,000 |
| Amount Not Paid | ₹2,00,000 |
| Percentage of Claimed Amount Paid | 60% |
Under the proposed approach, greater attention could be given to the relationship between the total amount claimed and the amount actually paid.
This would help consumers assess insurers more effectively rather than relying on a single headline settlement percentage.
It is important to remember that a partial payment does not automatically indicate wrongdoing. Deductions may arise from policy exclusions, deductibles, co-payments, sub-limits or other contractual conditions.
3. Clear Reasons for Rejected or Partially Approved Claims
Another important area under review is the process followed when insurance companies reject claims or approve only part of the requested amount.
According to the report, a second working group will examine standard guidelines for evaluating insurers and their grievance redressal systems.
The proposed framework aims to improve communication between insurance companies and policyholders.
If a claim is rejected or reduced, customers should receive a clear explanation of the decision.
This could help policyholders understand whether the deduction relates to an exclusion, waiting period, documentation issue or another policy condition.
Clearer explanations would also make it easier for customers to challenge decisions they believe are incorrect.
Greater consistency in reporting could help consumers compare different insurance providers before purchasing or renewing their policies.
4. Fewer Repeated Document Requests During Claim Settlement
Repeated requests for documents are another concern that the proposed reforms aim to address.
During health insurance claim processing, customers may be asked to submit medical reports, hospital bills, discharge summaries and other supporting documents.
When additional documents are requested at different stages, the process can become time-consuming.
IRDAI reportedly wants insurers to communicate documentation requirements more clearly at the beginning of the claim process.
This could help customers prepare the necessary paperwork without facing repeated requests.
The expected benefits include fewer administrative delays, improved communication and more efficient claim processing.
However, insurers may still require additional information when genuinely necessary to verify a claim or assess coverage.
5. ABHA ID May Be Used for Health Insurance Identification
The insurance regulator is also reportedly examining the possibility of using the Ayushman Bharat Health Account, commonly known as ABHA, as a common identifier in health insurance processes.
ABHA is part of India's digital health ecosystem and is intended to help individuals manage and access health-related information through supported digital services.
If appropriately integrated with insurance systems, it could simplify the identification and management of relevant health records.
Such integration may also help reduce duplication of information and improve coordination among participating healthcare organisations.
However, any use of ABHA in insurance processing would need to follow applicable privacy, consent and data protection requirements.
The proposal does not mean that every policyholder must immediately create or link an ABHA account to continue using existing health insurance benefits.
What Could Change for Health Insurance Policyholders?
The reported reforms are intended to address several common difficulties experienced during claim processing.
| Proposed Reform | Potential Benefit for Policyholders |
|---|---|
| Live Claim Tracking | Check claim progress through a mobile device |
| Greater Focus on Amounts Paid | Better understanding of actual settlement performance |
| Clear Claim Rejection Reasons | Improved transparency in insurer decisions |
| Simplified Documentation | Fewer unnecessary paperwork-related delays |
| Possible ABHA Integration | Easier management of supported health insurance information |
| Standardised Grievance Assessment | More consistent evaluation of customer complaints |
These changes could improve transparency and convenience if they are formally adopted and implemented.
What Should Policyholders Do While Waiting for the New System?
Until the proposed changes become operational, customers should continue following their insurer's existing claim procedures.
Policyholders should carefully review their coverage, waiting periods, exclusions, room-rent limits, deductibles and co-payment conditions.
During hospitalisation, it is advisable to retain copies of medical documents, claim forms, hospital bills and communications with the insurer.
Customers should also request written explanations whenever a claim is rejected or partially approved.
If a complaint remains unresolved, they can use the insurer's grievance redressal process and the applicable IRDAI complaint channels.
Keeping proper records can make it easier to resolve disagreements and understand the basis of a claim decision.
When Will the New IRDAI Health Insurance Rules Take Effect?
The supplied report describes these initiatives as proposals and areas of work being examined by dedicated groups.
It does not provide a confirmed implementation date for the real-time tracking system or the other proposed reforms.
Therefore, policyholders should not assume that every insurance company has already introduced these facilities.
The final scope, rollout schedule and operational requirements will depend on official regulatory decisions.
Conclusion
The reported IRDAI health insurance reforms could make the claim settlement process more transparent and customer-friendly.
Real-time tracking, clearer rejection explanations, improved settlement reporting and simpler documentation could help policyholders understand their claims and reduce unnecessary follow-ups.
The possible use of ABHA identification may also support more efficient digital processes, subject to appropriate safeguards.
For now, these initiatives should be viewed as proposed improvements rather than fully implemented requirements. Customers should monitor official IRDAI announcements and communications from their insurers for confirmed updates.