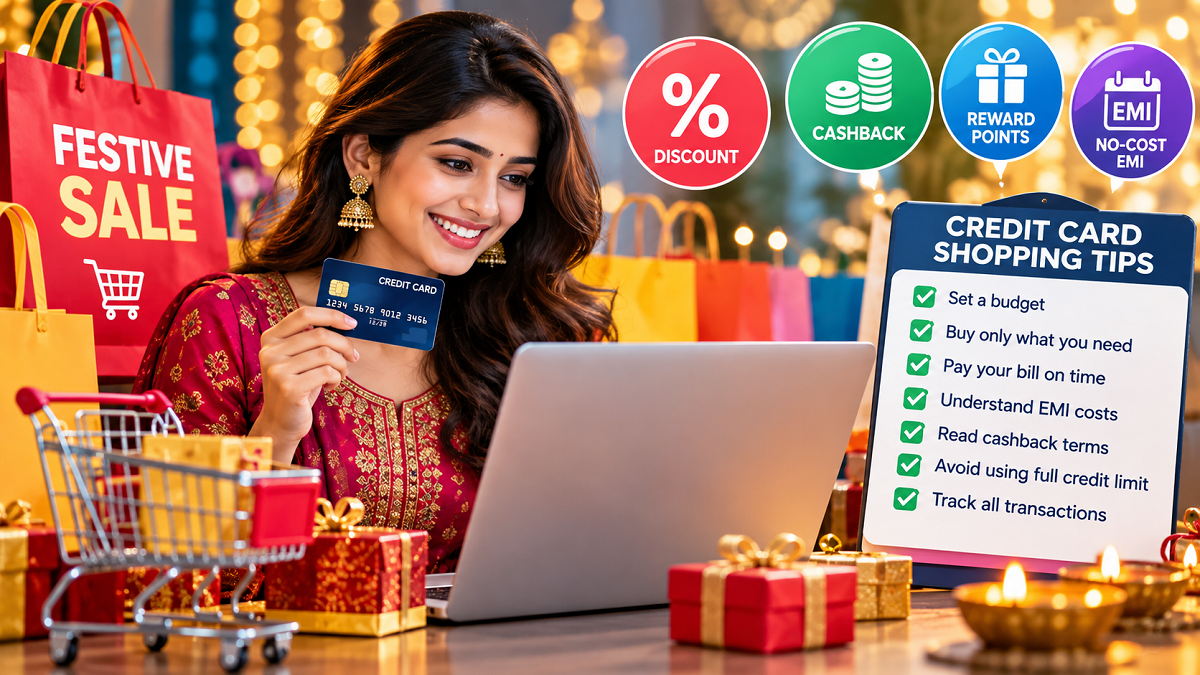
The festive shopping season often brings a flood of deals across online marketplaces, shopping malls and retail stores. Banks, credit card issuers and retailers also roll out attractive offers such as instant discounts, cashback, reward points and EMI options to encourage customers to spend.
While these promotions can help shoppers save money on planned purchases, they can also make it easier to spend more than intended. A high credit limit or an attractive EMI offer may create the impression that a purchase is affordable, but the actual financial impact becomes clear when the credit card bill arrives.
Using a credit card carefully can help you enjoy festive offers without putting unnecessary pressure on your monthly finances. Here are seven important points to consider before swiping, tapping or entering your card details during a sale.
1. Fix Your Festive Shopping Budget Before You Start
Before adding products to your cart, decide how much money you can comfortably spend.
Your available credit limit should never be treated as your shopping budget. For example, having a large unused limit does not automatically mean you can afford to spend the entire amount.
Instead, calculate your budget after considering your monthly income, household expenses, loan EMIs and other financial commitments. Once you have decided on a spending limit, try to stay within it even when tempting offers appear.
A pre-decided budget can reduce impulsive purchases and make the next credit card bill easier to manage.
2. Don't Buy Something Just Because It Is on Sale
Festive sales frequently advertise instant discounts, cashback deals, reward points and no-cost EMI options. However, a discount is useful only when you actually need the product.
Before making a purchase, consider whether you would have bought the item without the promotional offer.
It is also worth comparing the final payable price across different sellers. A product carrying a large advertised discount may not necessarily be the cheapest option once delivery charges, fees or other conditions are taken into account.
Focus on the amount you actually have to pay rather than the size of the advertised discount.
3. Pay Your Credit Card Bill in Full and on Time
Keeping track of your billing cycle and payment due date becomes especially important after heavy festive spending.
Paying the total amount due by the payment deadline can help cardholders avoid interest on carried balances, subject to the card issuer's applicable terms. It can also prevent late-payment charges.
Paying only the minimum amount due is very different from clearing the entire bill. While making the minimum payment may prevent the account from being immediately treated as unpaid under applicable terms, the remaining balance can continue to attract substantial interest and other charges.
If possible, plan your purchases so you can repay the entire outstanding amount when the bill becomes due.
4. Check the Real Cost Before Choosing an EMI
An EMI can make an expensive purchase appear affordable because the cost is divided into smaller monthly payments. However, shoppers should look beyond the monthly instalment.
Before converting a purchase into EMI, check the total amount payable over the entire tenure. This can include interest, processing fees, applicable taxes and other charges.
Even offers advertised as "no-cost EMI" can come with specific conditions. In some cases, discounts may be structured differently or certain processing charges and taxes may still apply.
Read the terms carefully and compare the total EMI cost with the price you would pay through a regular upfront transaction.
5. Read Cashback and Reward Offer Conditions
Seeing an advertisement offering cashback or a large instant discount does not necessarily mean every credit card transaction will qualify.
Banks and retailers can attach several conditions to promotional deals. An offer may require a minimum transaction value, purchase through a particular website or retailer, use of a specific card variant, or completion of the transaction within a defined promotional period.
There may also be a maximum cashback or discount cap.
For example, a percentage-based cashback promotion may sound attractive, but a maximum benefit limit could significantly reduce the actual amount received on a large purchase.
Check the eligibility conditions before paying rather than assuming the advertised benefit will automatically be credited.
6. Avoid Exhausting Your Available Credit Limit
Using a major portion of your available credit limit for festive shopping can make subsequent expenses more difficult to manage.
A large outstanding balance may leave little room for emergencies or necessary purchases before the next billing cycle. High credit utilisation can also be relevant to your broader credit profile.
Before making a major purchase, ask a simple question: Will I be able to comfortably repay this amount when my credit card bill arrives?
If the answer is uncertain, postponing or reducing the purchase may be financially safer than relying entirely on available credit.
7. Keep Checking Your Credit Card Transactions
Festive shopping can involve numerous transactions across multiple websites, apps and physical stores. Small purchases can quickly add up, making it difficult to remember the total amount spent.
Regularly review transactions through your bank's official mobile app, internet banking facility or credit card statement. Keeping a simple record of purchases can also help you stay within your planned budget.
Transaction monitoring has another important benefit: it can help you spot unfamiliar or incorrect charges quickly.
If you notice a transaction that you did not authorise, contact your card issuer through its official customer-support channel as soon as possible and follow the applicable card-blocking, reporting or dispute procedure.
Credit Cards Can Be Useful, but Spending Discipline Matters
Credit cards can offer convenience and valuable benefits during festive sales, particularly when purchases are already planned and promotional terms are properly understood. Problems generally arise when discounts encourage unnecessary purchases or when shoppers spend without considering how the bill will be repaid.
Before making a festive purchase, compare prices, understand EMI and cashback conditions, track your overall spending and keep enough money available to clear your dues.
The biggest festive discount may not always be the deal with the highest advertised percentage. A purchase that fits comfortably within your budget and can be repaid without accumulating expensive debt can ultimately be far more valuable.